 Skip to content

If you’re asking “Does homeowners insurance cover water damage in Stone Mountain Atlanta Georgia”, you’re probably standing in one of two situations right now: a pipe just burst under your kitchen sink, or a storm sent water pouring through your ceiling and you have no idea if your policy will pay for the repair. The honest answer is that it depends heavily on what caused the water, how suddenly it happened, and whether the damage could have been prevented with normal maintenance. Insurance companies draw a hard line between sudden, accidental water events and gradual, preventable ones, and that line determines whether your claim gets paid or denied.
Air Drop Water Restoration hears this question constantly, usually from homeowners standing in an inch of water who called their agent first and are now waiting on hold for an adjuster while the moisture keeps spreading. This guide walks through exactly which water damage scenarios a typical homeowners policy covers, which ones require a separate endorsement or flood policy, and what to do in the first hour after water damage hits your Stone Mountain property, because the faster you act, the stronger your claim and the smaller your repair bill.
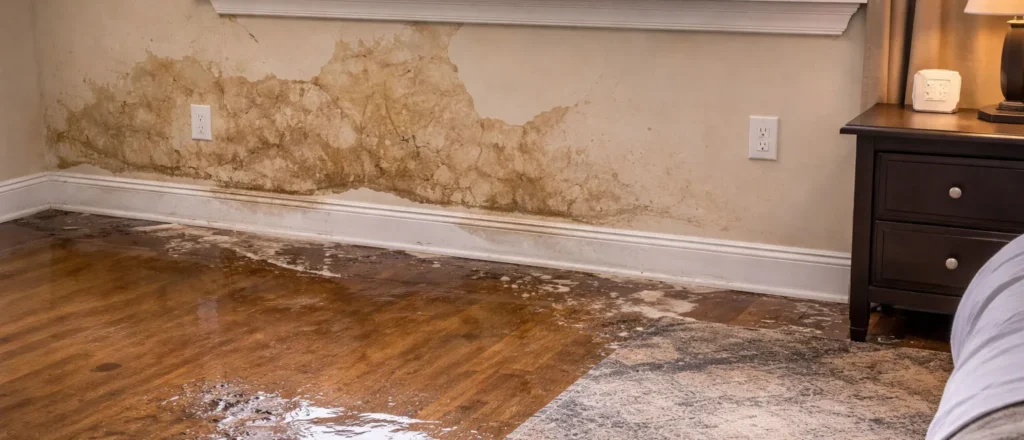
Dealing with water damage in your Stone Mountain home right now? Call Air Drop Water Restoration at +1 (678)-374-9247 for 24/7 emergency water damage assessment across metro Atlanta.
Does Homeowners Insurance Cover Water Damage?
In most cases, yes but only when the water damage is sudden and accidental. A pipe that bursts without warning, a washing machine hose that suddenly fails, or a storm-damaged roof that lets rain into your ceiling are typically covered perils under a standard homeowners policy, subject to your deductible and coverage limits. Damage that builds up slowly over weeks or months, a slow leak behind a wall, foundation seepage, or a roof that’s been deteriorating for years, is generally treated as a maintenance issue and excluded. Flooding from an outside source, like rising water from heavy rain or a nearby creek, almost always falls outside a standard policy and requires separate flood insurance.
Water Damage: Generally Covered vs. Generally Not Covered
| Usually Covered by Homeowners Insurance | Usually NOT Covered by Homeowners Insurance |
| Sudden, accidental water discharge | Gradual leaks that built up over time |
| Burst pipes (if the home was heated) | Foundation or basement wall seepage |
| Washing machine or appliance failures | Surface water entering from outside |
| Roof leaks caused by a storm or windstorm | Sewer or drain backup (without an endorsement) |
| Water heater sudden rupture | Flooding from a natural disaster or rising water |
| Contents damaged by a covered water event | Damage caused by homeowner neglect |
If your Stone Mountain home was affected by a flood, burst pipe, or storm event, contact your insurance carrier to start a claim, that process runs separately from anything a restoration company handles, but the two go hand in hand once water extraction and drying begin.
Read our Water Damage Restoration Services if water has already reached your home’s structure and you need help right now.
1. Does Homeowners Insurance Cover Burst or Frozen Pipes?
Yes, if the damage is sudden and accidental.
Most standard policies cover:
- Burst plumbing lines under sinks, behind walls, or in the ceiling
- Frozen pipes that rupture during a cold snap
- Sudden water discharge that damages walls, floors, and personal property
Coverage is typically denied if:
- The home was left unheated during freezing weather
- The homeowner knew about a leak or insulation problem and didn’t fix it
- The property sat vacant without being properly winterized
Many insurers now ask for proof that a home was kept above roughly 55°F, or that the water supply was shut off and pipes drained, before approving a frozen-pipe claim. Stone Mountain rarely sees the kind of deep freeze that damages pipes in northern states, but a sudden cold snap combined with an older home’s plumbing can still cause a burst, and the same coverage rules apply.
2. Does Homeowners Insurance Cover Water Damage from Appliance Failures?
Yes, in most sudden or accidental situations.
Covered causes generally include:
- A washing machine hose that bursts without warning
- A dishwasher or water heater that fails suddenly
- Accidental overflow from a mechanical malfunction
Coverage is generally denied if:
- The supply hoses were old, cracked, or never replaced
- The appliance had a known, unresolved issue
- The leak developed gradually rather than as a single event
Claim tip: Keep records of appliance maintenance and hose replacements (most manufacturers recommend replacing supply hoses every 3 to 5 years). Documentation like this is often what separates an approved claim from one flagged as a maintenance issue.
3. Does Homeowners Insurance Cover Roof Leaks in Stone Mountain?
Yes, if the leak is caused by a covered peril.
Covered causes typically include:
- Windstorms and severe thunderstorms
- Hail damage to shingles
- A tree limb or falling debris that punctures the roof
A policy that covers storm-related roof leaks will usually also cover the resulting damage to ceilings, walls, floors, and personal belongings inside the home. Coverage is typically denied when:
- The shingles were already old, curling, or deteriorated
- The roof had a documented, unresolved issue before the storm
- The homeowner failed to schedule routine maintenance or repairs
Roof claims are heavily scrutinized industry-wide right now, and many carriers ask for photos or a prior inspection report showing the roof was in good condition before a storm hit. Given Stone Mountain’s frequent summer thunderstorms, keeping dated photos of your roof’s condition is a smart, low-effort safeguard.
4. Does Homeowners Insurance Cover Sewer or Drain Backups?
No, not unless you’ve added a sewer backup endorsement.
Standard homeowners policies generally exclude:
- Sewer line backups into the home
- Septic system overflow
- Drain line failures
- Sump pump overflow
To get coverage for these scenarios, you typically need a Water Backup Endorsement, which is often an affordable add-on but usually caps payouts well below your dwelling coverage limit. If your Stone Mountain home has an older sewer connection or sits on a lower part of the lot, it’s worth asking your agent whether this endorsement is already on your policy.
5. Does Homeowners Insurance Cover Flooding from Storms or Natural Disasters?
No, standard homeowners insurance does not cover flooding.
Flooding caused by any of the following typically requires a separate policy:
- Heavy rainfall overwhelming drainage
- A nearby creek, stream, or stormwater system overflowing
- Storm surge or hurricane-related flooding
- Groundwater rising after saturated soil
These events fall under flood insurance, usually purchased separately through the National Flood Insurance Program (NFIP) or a private flood carrier. Metro Atlanta’s clay-heavy soil and hilly terrain mean that heavy rain can pool and intrude around foundations even outside a mapped flood zone, which surprises a lot of Stone Mountain homeowners who assumed they didn’t need flood coverage.
6. Does Homeowners Insurance Cover Foundation or Basement Seepage?
No.
Water that seeps in gradually through foundation cracks or basement walls is classified by most insurers as a long-term intrusion issue rather than a sudden event, which places it in the same excluded category as:
- Slow leaks that went unnoticed for weeks or months
- Poor grading or drainage around the foundation
- Deferred maintenance that allowed moisture to build up over time
If you’re not sure whether a specific basement water issue in your Stone Mountain home would be classified as sudden or gradual, our team can document the moisture pattern and cause during an inspection, that documentation is often exactly what your adjuster needs to make a determination.
7. Is Mold Covered After a Water Damage Event?
It depends on the cause and how quickly you acted.
Mold is generally covered when:
- It results directly from a covered water event, such as a burst pipe
- Mitigation and drying began promptly after the event
Mold is generally not covered when:
- It grew from a long-term, unaddressed leak
- The homeowner delayed calling for water extraction or drying
- Moisture buildup was traced to a maintenance issue
Many policies also cap mold remediation coverage at a set dollar amount, often well below the cost of a serious infestation, unless an optional mold rider was purchased. In Georgia’s humid climate, mold risk begins within 24 to 48 hours of sustained moisture exposure, according to EPA guidance, which is exactly why fast extraction and drying protect both your health and your claim.
Why Fast Response Matters for Water Damage Claims in Stone Mountain, Georgia
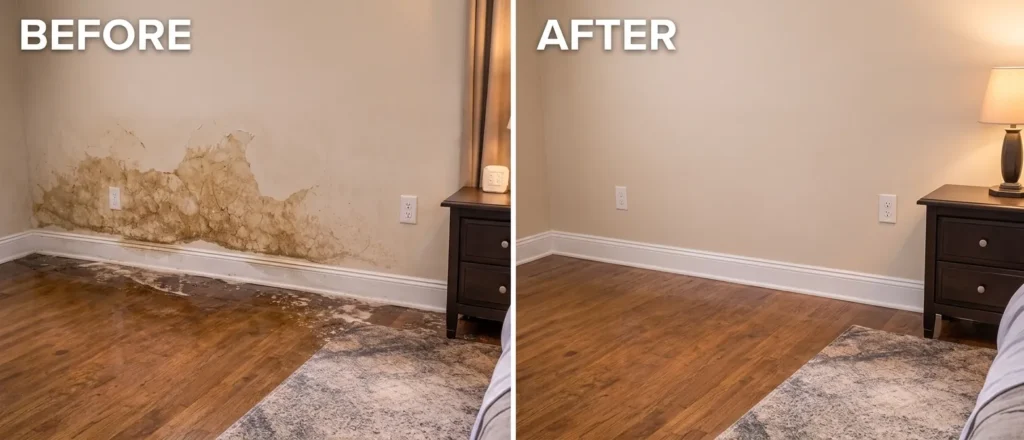
Stone Mountain’s humid subtropical climate, older housing stock in many neighborhoods, and heavy seasonal rainfall all raise the stakes when water damage strikes. Insurance adjusters also expect to see that you acted quickly to prevent the damage from getting worse, delaying mitigation can affect what a claim ultimately pays out.
- Mold risk begins within 24 to 48 hours of sustained moisture exposure, according to EPA guidance.
- Wood flooring and subfloors warp quickly when saturated, often requiring full replacement if drying is delayed.
- Electrical systems near water intrusion need professional inspection before power is restored, to avoid fire risk.
- Drywall and insulation act like sponges, holding moisture long after the surface looks dry.
The EPA’s mold and moisture guidance confirms the 24–48 hour window that makes rapid water extraction so important, both for your health and for your insurance claim.
The Air Drop Water Restoration Process for Home Water Damage Claims
Here’s what happens when you call us after a water damage event, from the moment we arrive to the final insurance documentation:
Step 1: Emergency Water Extraction
Industrial pumps and extraction equipment remove standing water immediately upon arrival, limiting how far the damage spreads.
Step 2: Moisture Mapping
Moisture meters and thermal imaging identify every affected area, including water hidden under flooring or behind walls, the kind of hidden damage that adjusters need documented.
Step 3: Structural Drying
Industrial air movers and dehumidifiers dry the structure to a verified standard, monitored until the job is complete.
Step 4: Damage Assessment and Documentation
We document affected materials, moisture readings, and cause-of-loss evidence, exactly what your homeowners insurance adjuster needs to process the claim.
Step 5: Repair and Restoration
Damaged drywall, flooring, and other materials are repaired or replaced to restore your home to pre-loss condition.
Read our Emergency Water Extraction Service for more on how quickly we respond across Stone Mountain and metro Atlanta.
Does Homeowners Insurance Cover Water Damage to Personal Belongings?
This depends on your specific policy, but many standard homeowners policies include personal property coverage that can extend to furniture, electronics, and other belongings damaged by a covered water event, such as a burst pipe, subject to your policy’s limits and deductible. Damage from an outside flooding source is typically excluded from personal property coverage the same way it’s excluded from dwelling coverage, and usually requires separate flood insurance. It’s worth reviewing your specific policy documents or speaking with your agent, since coverage details vary significantly by insurer and policy type.
Read our Commercial Water Damage Restoration services if the water event affected a business with computers, servers, or other equipment.
Not sure what your homeowners policy covers after a water event? Call Air Drop Water Restoration at +1 (678)-374-9247, we document everything your adjuster needs, from the first pump we run to the final repair.
Local Areas We Serve Near Stone Mountain
Air Drop Water Restoration provides water damage restoration throughout Stone Mountain and the surrounding DeKalb, Gwinnett, and Rockdale County communities, including:
| Stone Mountain Area | Nearby Communities |
| Stone Mountain, GA | Tucker |
| Lithonia | Decatur |
| Clarkston | Conyers |
| Redan | Lawrenceville |
| Pine Lake | Snellville |
Wherever you are in the Atlanta metro, our crews can reach you quickly, because while an insurance call can wait until morning, a wet house cannot.
Expert Tips: What to Do Before and After Filing a Water Damage Claim
As restoration contractors who work directly with homeowners and their adjusters, here’s what we recommend:
- Stop the water source immediately if it’s safe to do so, shut off the main valve or the appliance’s supply line.
- Photograph and video everything before you move or discard anything, including standing water and damaged belongings.
- Call a water damage restoration company right away, starting mitigation quickly protects both your health and your claim.
- Contact your insurance carrier promptly; many insurers require water damage to be reported within 24 to 72 hours.
- Keep every receipt for emergency repairs, temporary lodging, or equipment rentals related to the damage.
- Avoid discarding damaged materials until your adjuster or restoration team has documented them, unless they pose a safety hazard.
People Also Ask
Does homeowners insurance cover a burst pipe? Yes, in most cases, as long as the home was properly heated and the pipe burst suddenly rather than leaking gradually over time.
Does homeowners insurance cover flooding? Typically not. Flooding from an outside source, like heavy rain or a rising creek, usually requires separate flood insurance through the NFIP or a private carrier.
Does homeowners insurance cover sewer backup? Only if you’ve purchased a water backup endorsement; it’s excluded from most standard policies.
How long do I have to report water damage to my insurer? Most insurers expect a report within 24 to 72 hours of discovering the damage, since delays can affect coverage for related mold growth.
Frequently Asked Questions On Does Homeowners Insurance Cover Water Damage in Stone Mountain Atlanta Georgia
Does homeowners insurance cover water damage the same way everywhere in Georgia?
Policy language is generally consistent statewide, but coverage details, endorsements, and premiums can vary by insurer and by your specific policy, always confirm with your agent for your Stone Mountain address.
Can Air Drop Water Restoration help with my insurance claim?
We don’t process claims on your behalf, but we document all structural and property damage with photos and moisture readings, which supports the claim you file with your carrier.
If a storm caused water damage, does my policy cover both the roof and the interior?
Usually yes, if the roof damage stems from a covered peril like wind or hail, the resulting interior damage is typically covered under the same claim.
How fast can Air Drop Water Restoration respond after a water event in Stone Mountain?
We offer 24/7 emergency response across Stone Mountain and metro Atlanta, with technicians typically arriving the same day.
What’s the risk of waiting to start water extraction while I wait on my claim?
Significant, moisture left untreated for 24 to 48 hours creates conditions for mold growth, according to EPA guidance, and delayed mitigation can also affect what your claim ultimately pays.
Does my policy cover water damage to a finished basement?
It depends on the cause, sudden events like a burst pipe are typically covered, while gradual seepage through foundation walls generally is not.
Will my premium go up after filing a water damage claim?
Often, yes, especially for larger claims, and multiple water-related claims can sometimes lead to a non-renewal, your agent can explain how this applies to your policy.
Is it worth adding a sewer backup or flood endorsement in Stone Mountain?
For many homeowners in low-lying areas or with older sewer connections, yes — these add-ons are often inexpensive relative to the cost of an uncovered claim, but it’s a decision to make with your agent based on your property’s risk.
Conclusion: Know What Your Policy Covers Before Water Damage Strikes
So, does homeowners insurance cover water damage in Stone Mountain Atlanta Georgia? In most cases, sudden and accidental water events are covered, while gradual leaks, foundation seepage, sewer backups without an endorsement, and outside flooding generally are not. Knowing which category your situation falls into, and acting fast regardless, is what protects both your home and your claim.
Air Drop Water Restoration handles the property side of that equation for homeowners across Stone Mountain and metro Atlanta: certified water extraction, structural drying, and the documentation your adjuster needs, delivered fast enough to prevent mold and long-term damage.
Don’t let water damage spread while you sort out your coverage. Call Air Drop Water Restoration now at +1 (678)-374-9247 for 24/7 emergency water damage restoration across Stone Mountain and the greater Atlanta metro, certified technicians, transparent estimates, and insurance documentation from your very first call.